Fixed indexed annuities protect retirement savings from market volatility by guaranteeing principal against losses while linking growth to an index’s performance. Jacobs Financial Services incorporates these contracts into the Jacobs Retirement Roadmap™, offering Michigan pre-retirees and recent retirees tax-deferred accumulation with principal protection, unlike variable annuities.
Key Takeaways
- Sequence-of-returns risk compounds losses when withdrawals continue during a market decline.
- Fixed indexed annuities guarantee principal against losses while linking growth to an index.
- The Jacobs Retirement Roadmap™ segments assets by purpose and applies principal protection before volatility strikes.
Why does market volatility threaten your retirement?
Market volatility, bear markets, and recessions take a large bite out of retirement portfolios just when future retirees need stability most. The timing of a downturn matters more than its size.
What is sequence-of-returns risk?
Losses early in retirement create a compounding problem. When clients withdraw money from a portfolio during a down market, savings shrink faster. Recovery becomes harder even if the market bounces back later. This phenomenon is called sequence-of-returns risk, and it can negatively impact long-term financial security.
How do early losses compound?
The mechanics follow a predictable pattern:
- A market decline reduces the portfolio’s total value.
- Regular withdrawals continue at the same dollar amount.
- Each withdrawal removes a larger percentage of the remaining balance.
- The portfolio needs a larger percentage gain just to return to its starting point.
Market risk mitigation for retirees requires understanding this withdrawal math. Withdrawals during the decline make that recovery target steeper. Jacobs Financial Services addresses portfolio defense strategies through the Jacobs Retirement Roadmap™, which prioritizes principal protection alongside growth potential. Clients exploring how to reduce market risk before retiring benefit from reviewing protecting retirement savings before the first withdrawal occurs.
What is the first step to protect retirement from market downturns?
The first step is shifting focus from wealth accumulation to capital preservation and dependable income. This transition forms the foundation of market risk mitigation for retirees who can no longer afford deep portfolio losses.
Retirees face a distinct vulnerability: withdrawing money during a downturn locks in losses that compound over time. Protecting retirement from market downturns begins before the first withdrawal, not after a correction arrives.
Why does capital preservation matter more than growth in retirement?
Accumulation rewards risk. Retirement punishes it. Jacobs Financial Services prioritizes protection from market risk so hard-earned money stays safe during retirement years.
How does the Jacobs Retirement Roadmap™ address this shift?
The company uses the Jacobs Retirement Roadmap™ to build customized strategies that balance growth potential with reliable, guarded income. This roadmap approach incorporates proactive risk management, sequence-of-returns protection, and structured income planning.
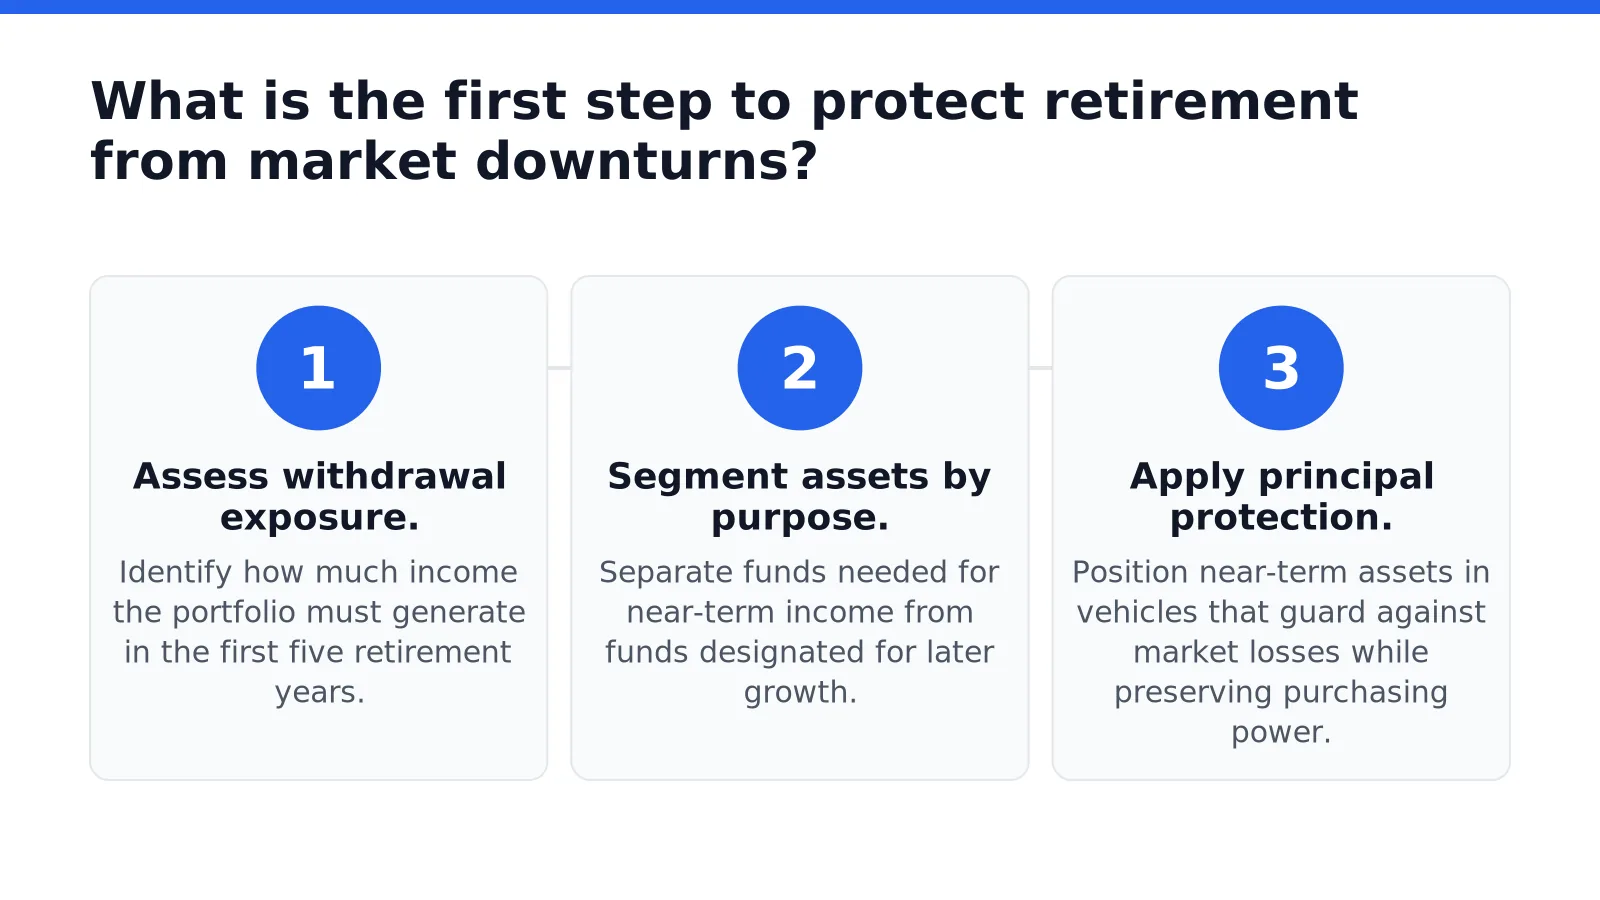
The process follows three ordered steps:
- Assess withdrawal exposure. Identify how much income the portfolio must generate in the first five retirement years.
- Segment assets by purpose. Separate funds needed for near-term income from funds designated for later growth.
- Apply principal protection. Position near-term assets in vehicles that guard against market losses while preserving purchasing power.
Portfolio defense strategies work best when implemented before volatility strikes. Retirees who wait until a downturn begins often discover their options have narrowed considerably.
How can you reduce market risk before retiring?
Market risk mitigation for retirees begins with shifting a portion of savings into vehicles that guard principal while still capturing growth. Fixed indexed annuities link growth to market index performance while protecting principal from losses. Without this shift, a downturn near retirement shrinks savings faster than withdrawals alone, leaving less capital to recover when markets rebound.
What strategies defend a portfolio against market downturns?
Effective portfolio defense strategies combine principal protection with tax-efficient growth. Fixed indexed annuities deliver both. Principal protection shields retirement funds from market downturns and volatility risks. Savings grow tax-deferred until withdrawal, maximizing compound growth potential over time. This dual structure helps pre-retirees avoid the sequence-of-returns risk that erodes nest eggs during the critical years just before and after leaving the workforce.
How do fixed indexed annuities help protect retirement from market downturns?
These contracts protect retirement from market downturns by eliminating direct market exposure. The account value never drops when the index falls. Growth credits apply when the index rises, subject to participation rates and caps. Jacobs Financial Services incorporates fixed indexed annuities into customized retirement roadmaps. Licensed insurance professionals at Jacobs Financial Services help align annuities with each client’s retirement goals, ensuring the strategy fits income needs and risk tolerance.
What steps reduce market risk before retiring?
- Assess exposure to market volatility retirement risks. Identify the percentage of savings tied to stocks and mutual funds that would lose value in a correction.
- Allocate a portion to principal-protected vehicles. Fixed indexed annuities remove that money from market swings while retaining growth potential.
- Structure for tax-deferred accumulation. Tax deferral preserves more capital for compounding, a critical advantage when time horizons shorten.
- Coordinate with guaranteed income sources. Align annuity payouts with Social Security and pension timing to cover essential expenses without selling assets during downturns.
What portfolio defense strategies work for retirees?
Effective portfolio defense strategies combine principal protection, inflation resistance, and legacy continuity. Jacobs Financial Services builds these defenses through the Jacobs Retirement Roadmap™, a structured approach that unites income, growth, and legacy planning.
How does market risk mitigation for retirees actually work?
Market risk mitigation for retirees starts with protecting principal from market losses. Jacobs Financial Services prioritizes protection from market risk so hard-earned money stays safe. This approach shields retirement savings from downturns that erode decades of accumulation.
What steps reduce exposure before retirement?
Retirees and pre-retirees reduce exposure through a deliberate sequence:
- Diversify income sources across products offering principal protection.
- Add inflation-fighting strategies that preserve purchasing power over a 20 to 30 year retirement.
- Establish legacy planning so assets transfer to loved ones beyond memories alone.
- Coordinate all three elements through the Jacobs Retirement Roadmap™ to minimize risk and build dependable income.
Which strategies defend against inflation and loss?
Portfolio defense strategies work best when inflation protection and downside protection operate together. Inflation-fighting strategies ensure purchasing power stays strong as living costs rise. Without them, fixed income loses real value year after year.
Legacy planning completes the defensive framework. Clients who skip legacy structuring risk leaving heirs with unnecessary complexity. Jacobs Financial Services integrates legacy goals into the same roadmap that governs income and growth decisions.
For retirees evaluating how to reduce market risk before retiring, managing risk in retirement investments requires coordinating these defenses rather than applying them in isolation. The Jacobs Retirement Roadmap™ provides that coordination.
How do you build a reliable income plan for retirement?
Building a reliable income plan starts with structured income planning that prioritizes security over speculative growth. A roadmap approach protects retirement savings from the damage that market downturns inflict during the early withdrawal years. Without this protection, sequence-of-returns risk drains portfolios faster than most pre-retirees anticipate.
Jacobs Financial Services specializes in helping individuals who are recently retired or preparing to take that next big step. The most common question clients ask is whether they have saved enough. Rather than chasing risky growth strategies, the company focuses on market risk mitigation for retirees through deliberate, defensive positioning.
What is the first step in creating retirement income you cannot outlive?
The process begins with a candid assessment of essential expenses versus discretionary spending. Clients identify the income floor required to cover housing, healthcare, and food before allocating assets to lifestyle goals. This hierarchy prevents market swings from threatening basic needs.
Portfolio defense strategies form the foundation of the Jacobs Retirement Roadmap™. The approach layers guaranteed income sources with growth-oriented holdings, creating a buffer that absorbs volatility without forcing withdrawals from depressed assets.
How does a roadmap approach protect against market downturns?
A structured roadmap sequences income sources to protect retirement from market downturns during the critical first decade of retirement. Fixed income streams cover near-term expenses while growth assets remain untouched, giving them time to recover from inevitable corrections.
The strategy addresses how to reduce market risk before retiring by shifting allocation gradually during the final working years. This transition moves assets from accumulation mode to distribution mode before the first retirement paycheck arrives.
Market volatility retirement planning succeeds when income remains steady regardless of what the S&P 500 does in any given quarter. Jacobs Financial Services builds plans around this principle, incorporating tax-efficient withdrawal sequencing detailed in its retirement income strategy framework. Retirement represents peace of mind, and a properly constructed income plan lets clients enjoy that peace fully.
FAQ
What is sequence-of-returns risk?
Withdrawing money during a down market shrinks savings faster, making recovery harder even if the market bounces back later.
How does the Jacobs Retirement Roadmap™ protect retirement savings?
It segments assets by purpose and applies principal protection before volatility strikes, prioritizing capital preservation and dependable income through fixed indexed annuities that guarantee principal against losses.
Conclusion
Protecting retirement savings from market volatility requires a deliberate shift from growth-focused accumulation to principal-protected distribution. By assessing exposure, allocating to fixed indexed annuities, and coordinating guaranteed income with Social Security timing, you build a defense that keeps essential expenses covered regardless of market conditions. The Jacobs Retirement Roadmap™ sequences these protections so your savings withstand downturns without forcing withdrawals from depressed assets. Take the next step by evaluating your current allocation against this framework, ensuring your retirement income remains steady and your peace of mind intact.